If every bill, childcare form, and insurance decision runs through you, your death would create two problems at once: your child would lose you, and another adult would have to reconstruct the household you managed. End-of-life planning lets you shape that handoff before a crisis does.
You do not need a perfect forecast or an elaborate estate. You need a workable chain: the right adult can care for your child, the right person can manage the money, funds are available for the transition, and essential instructions can be found. Because estate, family, insurance, and tax rules vary by location, use the framework below to organize your decisions, then have a qualified local professional confirm the legal details.
Build the plan around the handoff, not only the funeral
Final arrangements matter, but they are only one part of the problem. Your first planning question is: who takes over each responsibility when you cannot?
A single name is rarely enough. Caring for your child, administering your estate, and managing money for your child are different jobs. One person may be right for all three, but do not assume that automatically.
- Choose an immediate contact. This is the adult who could respond quickly, collect your child from childcare, follow the child’s routine, and contact the people named in your legal plan. Being the immediate contact does not, by itself, make that person the legal guardian.
- Name your preferred guardian and a backup. Consider the person’s willingness, health, location, household stability, relationship with your child, and ability to handle day-to-day parenting. Ask before naming anyone.
- Choose an estate representative. Often called an executor, this person deals with institutions, documents, debts, claims, and distributions. Reliability and organization matter more than family seniority.
- Decide who should manage your child’s money. A trustee or other legally authorized manager may control funds under the arrangement created for your child. The best caregiver is not always the best financial administrator.
- Tell each person what role you have in mind. Confirm that they accept it, name a backup, and tell both people where the signed documents and emergency information are kept.
If your child’s other legal parent is living, do not assume that naming someone else in a will overrides that parent’s rights. Guardianship decisions depend on local law, existing custody arrangements, and the child’s circumstances. A local estate or family lawyer should review this part of the plan.
If there is a history of family violence, stalking, coercive control, or a serious custody dispute, do not place confidential addresses, childcare locations, or account access details in a file that several relatives can open. Ask a lawyer or support professional how to create a safe disclosure plan.
Calculate the financial gap your child would actually face
The funeral bill is not the whole number. The adult caring for your child may also face housing costs, childcare changes, time away from work, travel, legal administration, and the loss of the income that kept your household running. A modest amount of preparation can keep final expenses and administrative confusion from becoming a second crisis.
Build a simple worksheet using four groups:
- Immediate costs: final arrangements, travel, urgent childcare, professional fees, and unpaid household bills.
- Household continuity: housing, utilities, food, transportation, childcare, and other costs required to keep your child safe and settled.
- Transition costs: a move, a housing deposit, replacement furniture or baby equipment, time away from work for the caregiver, and changes to childcare.
- Longer-term support: the portion of future housing, care, education, health, and everyday living costs you want your resources to cover.
Then list resources that may be available: cash, insurance, employment-related benefits, investments, property, and any survivor or family benefits for which your child might qualify. Verify eligibility and access instead of relying on assumptions.
Your working coverage gap is the total need minus the resources that would actually be available. Do not count an asset as immediate cash until you know who can access it, under what authority, and what process the institution requires. A home or investment account may have substantial value while still being impractical for an urgent grocery, rent, or childcare payment.
If life insurance is part of the solution, review more than the headline benefit. Record the policy owner, insured person, beneficiary, coverage amount, premium payer, policy term, renewal conditions, exclusions, and claim contact. If coverage comes through your employer, find out what happens when your employment changes or ends. Do not assume workplace coverage follows you automatically.
When money is tight, begin with the steps that do not require buying a product: inventory what you already have, check beneficiary records, identify the real cash gap, and organize your documents. You can then compare insurance options against a defined need instead of accepting a sales estimate. A financial planner should be able to explain how they are paid, any product-related conflicts, and the assumptions behind the recommended amount.
Make the will, beneficiaries, and account ownership agree
An estate plan is a system, not a single document. A carefully written will can still produce an unintended result if an old beneficiary form or account-ownership arrangement points somewhere else.
- Will: states how property handled through your estate should be distributed and names the person you want to administer it.
- Guardianship language: records whom you want considered for your child’s care. The legal effect and final decision depend on the law where you live.
- Trust or other child-inheritance arrangement: sets out who manages money, what it may be used for, and when control passes to your child.
- Beneficiary designations: direct certain insurance policies, registered plans, retirement accounts, or similar assets according to the applicable contract and local rules.
- Ownership and title records: show who legally owns bank accounts, investments, vehicles, real estate, and debts.
- Incapacity documents: authorize trusted people to make financial or personal decisions while you are alive but unable to act. These are not replacements for an estate plan that operates after death.
Do not name a young child directly on a beneficiary form until a lawyer has explained the consequences. Minors generally cannot manage substantial funds themselves, and an institution or court process may determine who holds the money if you have not created a valid arrangement. The correct structure and terminology vary by jurisdiction.
For every policy and account with a beneficiary field, request the current designation from the institution. Do not rely on memory or a copy of an unsigned form. Compare the recorded designation with your will and the plan for managing your child’s inheritance. Ask a lawyer which instruction controls when documents conflict.
Bring custody orders, parenting agreements, child-support arrangements, and relevant parentage documents to the legal appointment. They affect the real-world handoff and should not be treated as a separate subject.
Tailored advice is especially important if your child has a disability or receives income-tested support, you own a business, you have property in more than one jurisdiction, you are part of a blended family, you have significant debt, the intended guardian lives elsewhere, or conflict with a co-parent is likely. A generic online form may not account for these complications.
Create an emergency file someone can use under pressure
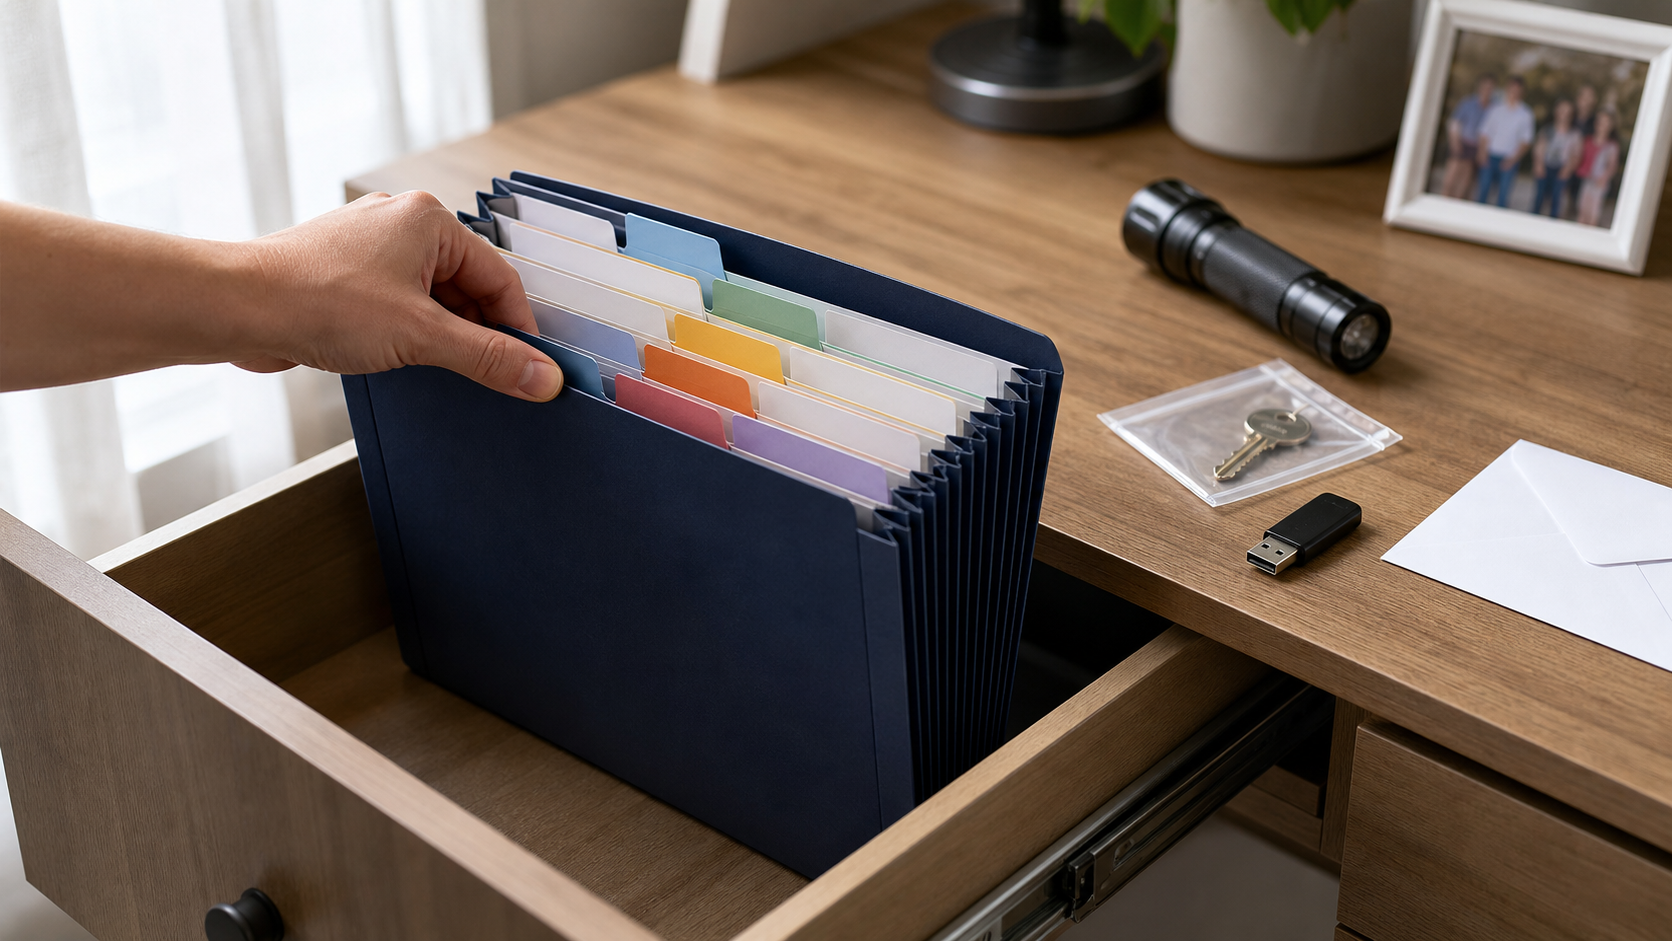
A signed plan is not useful if nobody can find it. Create a protected paper or digital file, and put a one-page “Start here” sheet at the front. That page should identify the immediate caregiver, backup contact, estate representative, lawyer, insurance contact, and location of the original will. It should not contain every password or sensitive account credential.
Organize the full file into clear sections:
- Your child’s essentials: full legal name, identification documents, childcare contacts, authorized pickup information, health contacts, allergies, medications, feeding needs, sleep routine, and comfort items. Update these details frequently during the first three years because routines and care needs change quickly.
- Legal documents: the original will or its confirmed location, guardianship instructions, trust documents, incapacity documents, parenting agreements, custody orders, and contact information for the lawyer who prepared them.
- Financial inventory: each institution, account type, owner, approximate value and date, last few identifying digits, and named beneficiary where applicable. Avoid storing full account numbers unless the file is strongly protected.
- Insurance: insurer, policy number, type of coverage, insured person, beneficiary, premium method, adviser or agent, and claims contact.
- Income and benefits: employer contact, payroll or benefits administrator, pension or retirement provider, and any programs that may need to be notified.
- Property and debts: mortgage or lease, vehicle title or loan, credit accounts, personal loans, jointly held obligations, storage units, and the location of deeds or ownership records.
- Household operations: recurring bills, automatic payments, childcare fees, utilities, subscriptions that should be cancelled, pet care, and any payment that could disrupt housing or care if missed.
- Digital access: instructions for locating your password manager or digital-estate plan. Keep the recovery method secure and separate from an openly accessible household folder.
- Personal wishes: final-arrangement preferences and messages for your child. Label these separately from legally binding instructions so nobody has to guess which is which.
Tell your primary and backup contacts where the file is and how they would gain access. They do not need unrestricted access to all of your financial data while you are well. They do need enough information to locate the plan during an emergency.
Set a recurring calendar reminder to review the file. Review it sooner after a birth, move, new relationship, separation, custody change, job change, major purchase, new debt, insurance change, or death or incapacity of someone named in the plan. Replace outdated copies so an old version is not mistaken for the current one.
Key takeaways: make a usable first pass
- Name a preferred guardian, backup guardian, estate representative, and money manager. Confirm that each person is willing to serve.
- Estimate the financial gap created by your lost income and caregiving work, not only the cost of final arrangements.
- List every existing policy, benefit, account, asset, and debt before deciding whether you need additional coverage.
- Ask each institution to confirm its recorded beneficiary and ownership information.
- Take your role list, asset inventory, custody documents, and beneficiary records to a qualified lawyer in your jurisdiction.
- Create a protected emergency file and a short “Start here” page that trusted contacts can find.
- Review the entire plan when your family, work, finances, or chosen helpers change.
Your next step does not have to be dramatic. Write down the four names you are considering for immediate care, guardianship, estate administration, and money management. Then contact them. Once the people are real and willing, the legal documents, coverage calculation, and emergency file have a clear structure to follow.
References